Clear thinking for complex, cross-border wealth.
Integrated financial planning for Chinese-Canadian families navigating wealth across borders — where tax, estate, and asset structure rarely fit a standard template.
Eleven calculators, regularly updated articles, and checklists you can actually use. Many questions answer themselves here.
BMO · Scotiabank GAM
· Canaccord Genuity
Former employers · 7+ years in Canadian wealth management
Bilingual · Cross-border
· Independent
You may recognize some of this
If so, we should talk.
Not sure? Take the three-minute cross-border check →
New to all of this? Our articles are the better place to start →
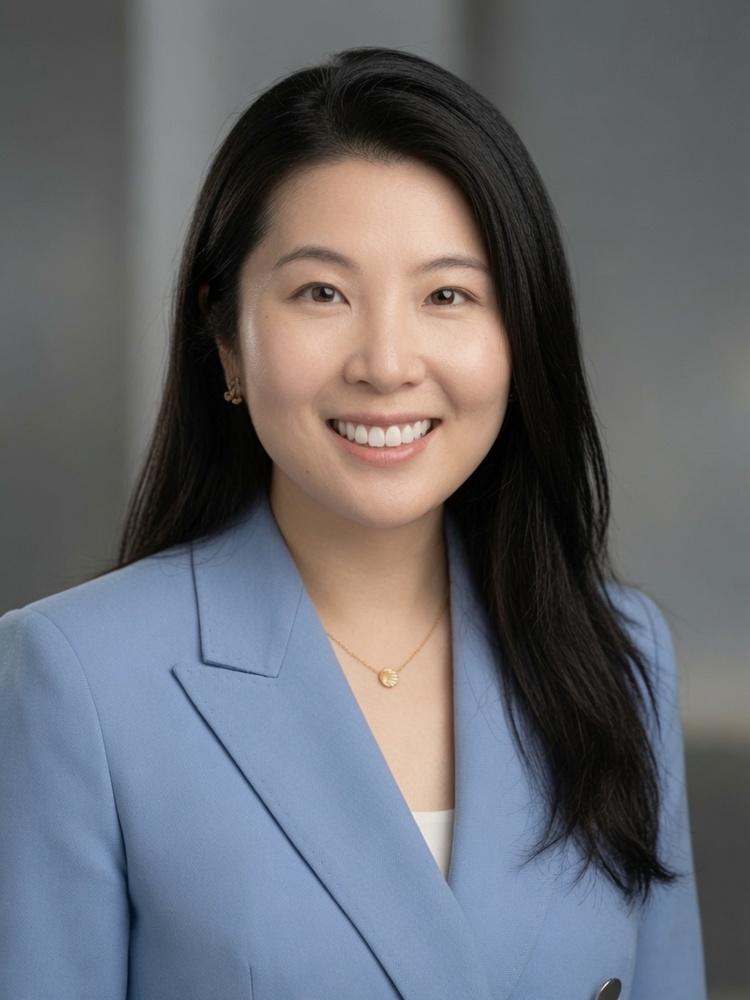
Lucinda Xue
CFP® · CIWM® · CIM® · PFP®
Seven-plus years in Canadian wealth management — formerly at BMO, Scotiabank Global Asset Management, and Canaccord Genuity — before founding Lucid.
The plan is completed independently and billed on its own. Once it's delivered, whether to implement — and with whom — is entirely your decision.
Meet LucindaWhere four disciplines meet
Complex cross-border situations sit at the intersection of tax, estate, insurance, and investments — and they work best when those pieces are considered together. At Lucid, one advisor is responsible for how they connect: accounting, planning, insurance, and investment training brought to one table, and the same set of eyes on the whole picture over time.
The whole picture on one map
Growth, transfer, cash flow, tax, and risk considered as one system — not each calculated on its own
Diagnose first, then discuss solutions
We work out where the real problem is before talking about what to do
Independent practice
Tied to no bank, insurer, or investment firm; advice answers to your goals, and all compensation is fully disclosed
How scenario testing informs your plan
A tax bill at death that could have been planned for.
Capital that sat idle for a decade.
A wealth transfer that shrank more than it ever needed to.
A structure that has never been tested can carry costs that stay quiet for years, surfacing well after the decision that created them. Rather than relying on projections that hold only while markets cooperate, we test your structure against the scenarios that matter most to families:
Our planning engine, Conquest, is the same platform trusted by six of the top ten banks in North America; on top of it, we add Lucid's own cross-border analysis — assets in China, remittance paths, and tax questions spanning both countries. The tools widen what we can see; the judgment stays human.
Severe, prolonged market downturns — whether your growth and transfer goals survive multi-year declines, not just one bad year.
Longer life, and late-life medical or care costs — whether the plan still holds if you live well past expectations.
Rising interest rates — whether any borrowing or insurance structure stays solid when conditions turn against it.
Real estate concentration — what happens when property prices pull back or liquidity tightens.
The transfer itself — whether there is enough liquidity at handover, so assets never have to be sold under pressure.
Scenario testing helps us understand how changing conditions could affect your plan and where preparation may be needed.
See exactly what a completed plan looks likeThis is how we think about structure — not a promise of any outcome. Every family's situation is assessed individually.
Three questions, answered directly
Will I be taxed when I bring the proceeds of a China property sale into Canada?
The transfer itself generally isn’t taxed on its own. What actually drives the bill: the day the property sells, your Canadian tax-residency timeline, the property’s cost basis under Canadian rules, and whether tax paid in China can be credited. Getting the sequence right or wrong can be a six-figure difference.
Canada has no estate tax — do I still need estate planning?
There is no tax called an estate tax, but there is deemed disposition: at death, your assets are treated as sold at market value, and decades of gains settle on one final return — with any RRSP/RRIF balance included in full (a rollover to a spouse can usually defer this — deferral, not elimination). The bill arrives on a deadline; real estate and private company shares do not sell on one. What needs planning is liquidity at that moment, not the tax itself.
I already have an accountant, a lawyer, and a bank advisor. Why a planner?
Each of them does their part well: this year’s return, the documents on file, the account they manage. The most expensive mistakes in cross-border families happen at the seams between them. A planner’s job is not to replace them — it is to put those professional opinions on one page.
Planning comes first.
We start by understanding your situation, then discuss recommendations that fit. From there, we build a clear plan, and support implementation only if it makes sense.
Not sure where to start?
Start by writing down your situation and the question you're weighing. Every message is read. We'll reply to the email address you provide with a suggested starting point — and if paid planning isn't needed at this stage, we'll say that too. Free, with no call to book.